S&P500 Daily Action Areas & Price Targets 13/10/26
S&P500 Daily Action Areas & Price Targets 13/10/26
***QUOTING ES1!(Z CONTRACT LEVLES) FOR CASH US500 EQUIVALENT LEVELS, SUBTRACT POINT DIFFERENCE***
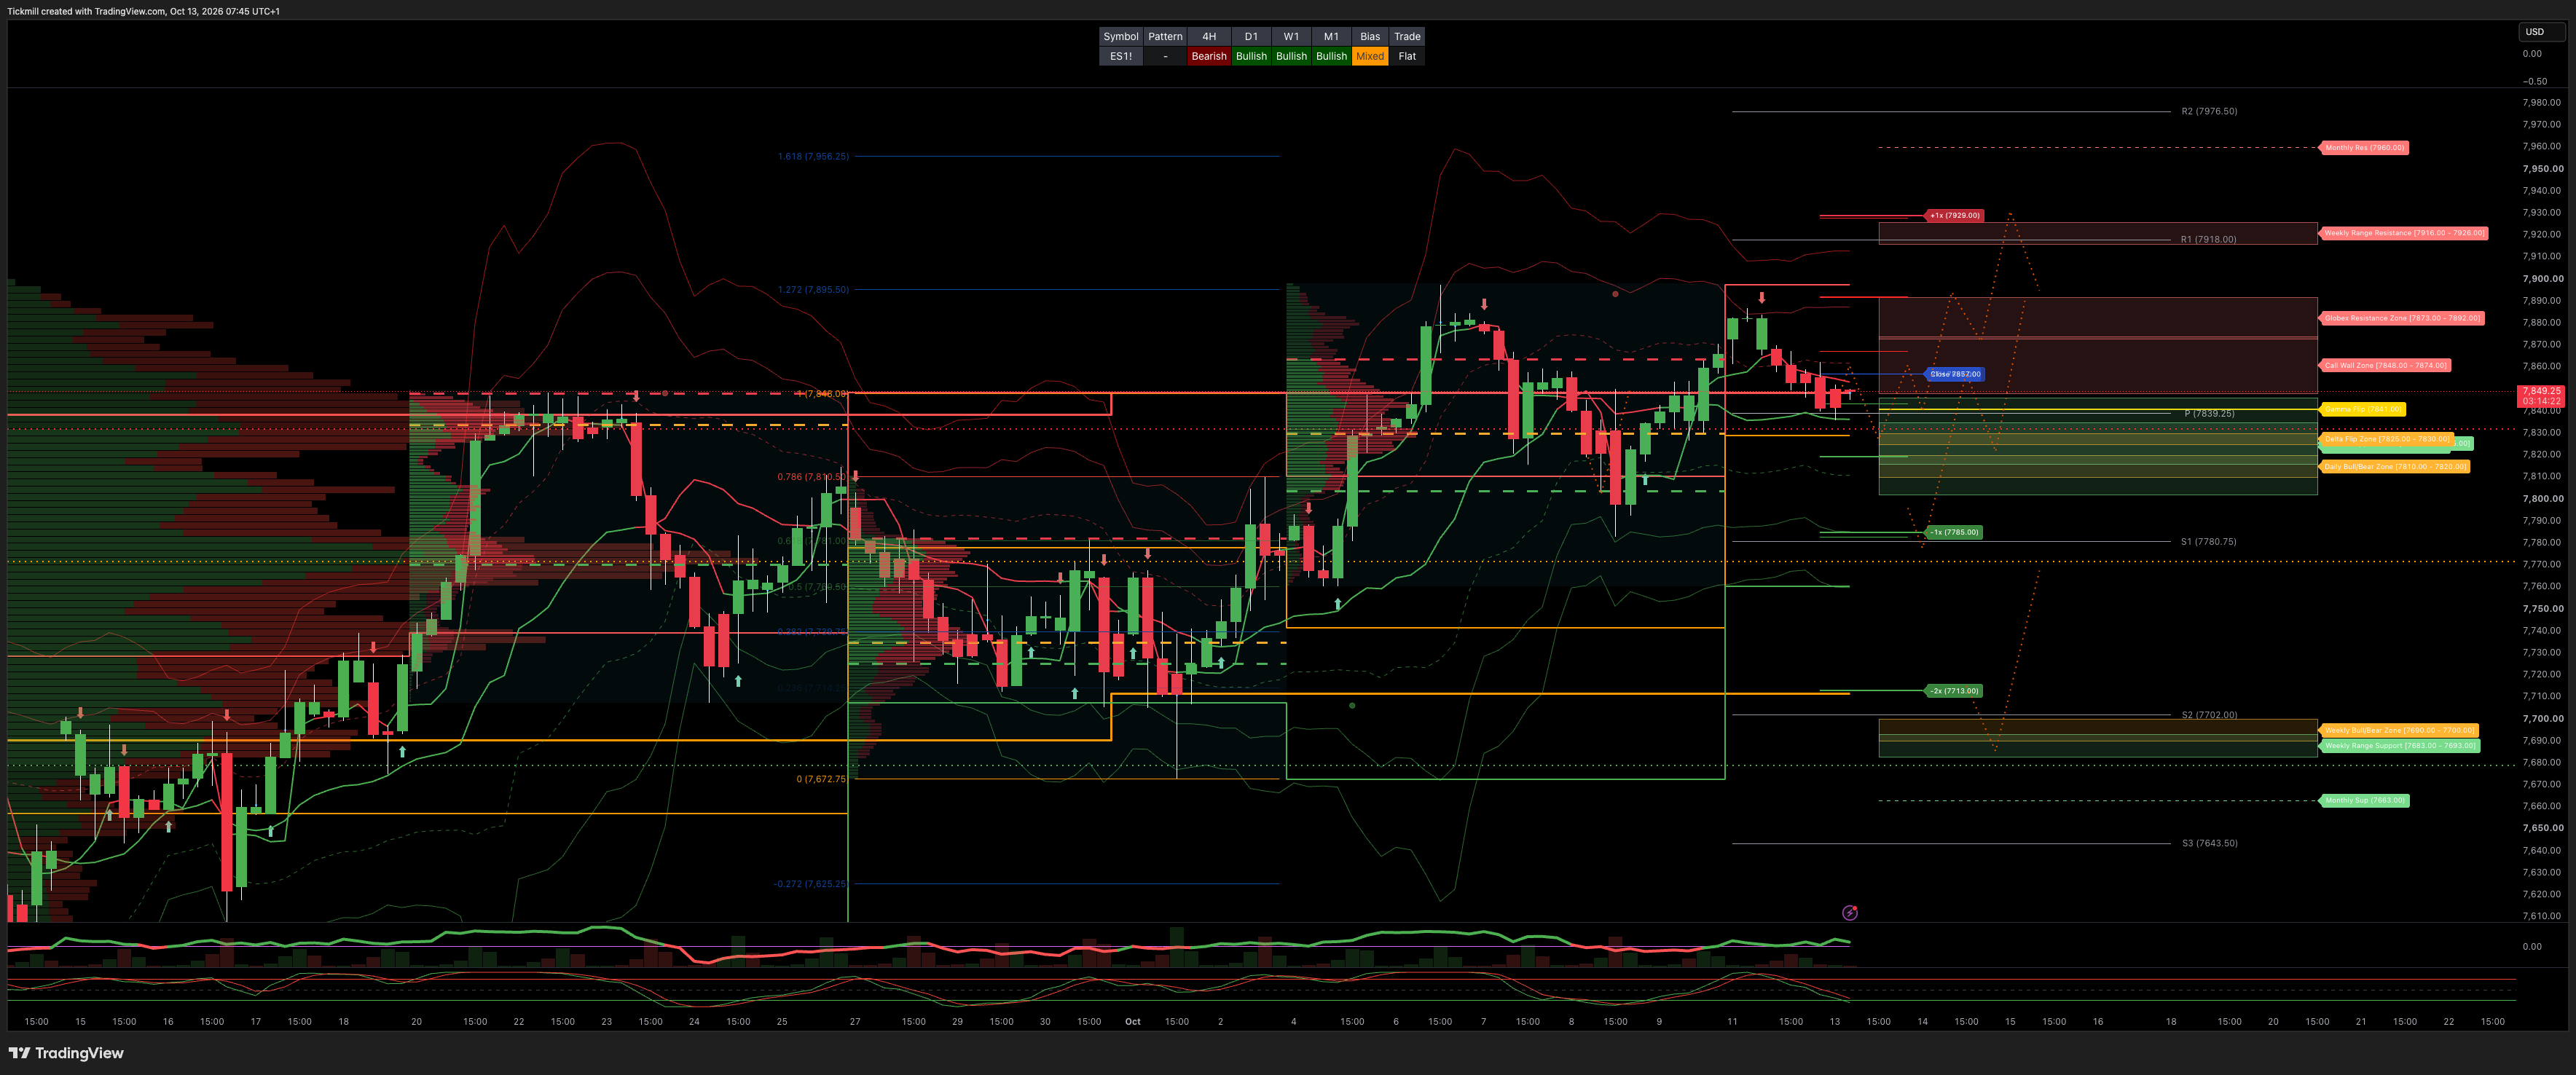
MONTHLY-WEEKLY& DAILY LEVELS
MONTHLY BULL BEAR ZONE 7440/7400
MONTHLY RANGE RES 7960 SUP 7663
WEEKLY BULL BEAR ZONE 7700/7690
WEEKLY RANGE RES 7926/16 SUP 7683/93
DAILY BULL BEAR ZONE 7820/10
GLOBEX RANGE SUP 7835/16 RES 7873/92
GAMMA FLIP 7841
DELTA FLIP 7825/30
CALL WALLS 7848/74
PUT WALLS 7846/02
UNFILLED GAPS 7741
DAILY STRUCTURE - BALANCE - 7897/7778
WEEKLY STRUCTURE - OTFH - 7778
MONTHLY STRUCTURE - OTFH - 7542
VIX BULL BEAR ZONE 17.7
VVIX-to-VIX ratio of 5.65 sits right in the historical "sweet spot" for market positioning, but its composition reveals a quiet shift in market dynamics
PRIMARY TRADES & TARGETS
LONG ON REJECT/RECLAIM OF THE DBBZ TARGET DAILY RANGE RES > ATH’S
***ADDITIONAL SETUPS & TARGETS HIGHLIGHTED ON THE CHARTS***
(I FADE TESTS OF 2 SIGMA LEVELS ESPECIALLY INTO THE FINAL HOUR OF THE NY CASH SESSION AS 90% OF THE TIME WHEN TESTED THE MARKET WILL CLOSE ABOVE OR BELOW THESE LEVELS)
SPX PUT/CALL RATIO 1.13 (The numbers reflect options traded during the current session.) A put-call ratio below 0.7 is generally considered bullish, and a put-call ratio above 1.0 is generally considered bearish.
JHEQX Upside cap (~7,920–7,950): Dealer gamma hedging at this call strike creates resistance, with market makers likely selling futures into strength and limiting volatility. Downside cushion (~7,270): If SPX drops 5% into Q4, long put gamma may force dealers to buy futures as the index falls, helping stabilize prices. Expiration: December 31, 2026. Strong pinning effects are likely near key strikes into year-end expiration.
DEC2025 OPEX to DEC2026 OPEX is 945 points giving us a range of [5889,7779]
Notes On Structure Implications
Balance: This refers to a market condition where prices move within a defined range, reflecting uncertainty as participants await further market-generated information. Our approach to balance includes favouring fade trades at the range extremes (highs/lows) while preparing for potential breakout scenarios if the balance shifts.
One-Time Framing Higher (OTFH): This represents a market trend where each successive bar forms a higher low, signalling a strong and consistent upward movement.
One-Time Framing Lower (OTFL): This describes a market trend where each successive bar forms a lower high, indicating a pronounced and steady downward movement.
GOLDMAN SACHS FICC & EQUITY TRADING DESK VIEWS
THE TAKE: MARKET BREADTH DIVERGENCE & THE BULLISH CASE FOR HIGH CONCENTRATION
The disconnect between headline benchmark levels and the underlying equity market remains one of the most extreme structural features of current price action. While the S&P 500 continues to sit within 1% of its all-time highs, the median constituent stock is down -16% from its own 52-week peak. By Goldman Sachs' preferred internal measures, market breadth has deteriorated to its weakest level since the Dot-Com Bubble.
The clearest manifestation of investor apprehension beneath the surface is the aggressive flight to quality. The GS Quality Factor has surged over +16% across the past 8 weeks—a magnitude of flight-to-safety capital allocation not seen since the March 2020 COVID shock. Investors are favoring quality at a pace typically reserved for severe crisis periods, even as the index trades near record highs.
Despite widespread client anxiety over market narrowness, historical study indicates that extreme concentration is actually a bullish signal over a 1- to 3-month horizon. In a historical study of 13 episodes since 1995 where the 10 largest S&P 500 stocks outperformed the equal-weighted index (RSP) by >8% over 3 months (vs. 855 bps today), subsequent SPX returns averaged +10.1% over 6 months and +19.6% over 12 months (outperforming baseline historical medians of +6.9% and +15.0%).
POSITIONING & HEDGE FUND FLOW DYNAMICS
GS Sentiment Indicator & Leverage Metrics:
The GS US Equity Sentiment Indicator has plunged to -1.3 SD, reaching levels where historical forward risk/reward turns strongly asymmetric to the upside.
Global Fundamental L/S Net Leverage sits in the 6th percentile over a 1-year lookback (and the 2nd percentile when isolating US L/S).
Overall Hedge Fund Net Leverage is at the 10th percentile, while Gross Exposure remains elevated—reflecting heavy risk on books with minimal directional conviction.
Fundamental Alpha Performance Drag:
Fundamental L/S funds lost -70 bps between October 2 and October 8, driven by negative alpha across both long and short books.
US single stocks were net sold for a third consecutive week, with short sales outpacing long buys.
Sector Rotation & Extremes:
Technology Reversal: After being net bought in 4 of the prior 5 weeks, Technology was by far the most net sold sector last week via long liquidations and fresh short additions. Tech L/S ratio has fallen to 1.8 (17th percentile over 5 years), despite gross allocations holding in the 97th percentile.
Industrials Inflows: Saw its fastest pace of net buying since January (+1.8 SD), driven almost entirely by new long buying following 5 weeks of continuous supply.
Financials & Software: Attracted notable net buying and relative strength ahead of Q3 bank earnings.
Consumer Staples & Biotech De-Grossing: Staples has been net sold in 7 of the last 8 weeks (97th percentile shorting, pushing its L/S ratio to 3rd percentile over 5 years). Biotech has experienced its largest 8-week percentage de-grossing in over 5 years.
MACRO HEADWINDS & DERIVATIVE HEDGING OPPORTUNITIES
Rates & Yield Curve Asymmetry: Following the 10-Year Treasury yield breaking above 5.0% (currently hovering near 5.2–5.3%), GS Rates strategists view yield asymmetry as skewed toward lower rates, accompanied by a peak and reversal in interest rate volatility.
Oil & Geopolitical Risk Premium: Brent crude moderation toward $90/bbl by December remains the baseline, but commodities strategists emphasize upside risks tied to $20+/bbl of geopolitical risk premium and Strait of Hormuz supply concerns.
Nvidia (
NVDA) Implied Volatility Anomaly:Implied volatility for Nvidia (
NVDA) downside options has dropped to levels not seen since prior to the COVID shock.The desk identifies NVDA downside options as a compelling opportunity for portfolios seeking a cost-effective tail-risk hedge against an unwind in AI crowding or quality factor concentration.
SUMMARY TACTICAL DESK TRADE MATRIX
Strategy / Target | Directional Bias | Structural Rationale & Implementation |
S&P 500 Index (SPX) | Bullish (1–3 Months) | Supported by light positioning (-1.3 Sentiment Indicator), 2nd percentile US net leverage, and bullish forward odds post-extreme concentration. |
Nvidia ( | Tactical Vol Long | Implied downside volatility at multi-year pre-COVID lows; provides cheap tail-risk protection against AI/Quality factor unwinds. |
Industrials ( | Sector Rebalancing | Industrials seeing fastest net buying (+1.8 SD) since January; capital moving into non-AI cyclical pockets. |
Outperformance Call Options | Relative Value | Monetize market broadening via Dec31 |
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 68% and 74% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
Patrick has been involved in the financial markets for well over a decade as a self-educated professional trader and money manager. Flitting between the roles of market commentator, analyst and mentor, Patrick has improved the technical skills and psychological stance of literally hundreds of traders – coaching them to become savvy market operators!