FTSE Finish Line 29/9/26: Pharma & Mining Gains Fade, Policy Risks & Energy Drag
FTSE Finish Line 29/9/26: Pharma & Mining Gains Fade, Policy Risks & Energy Drag
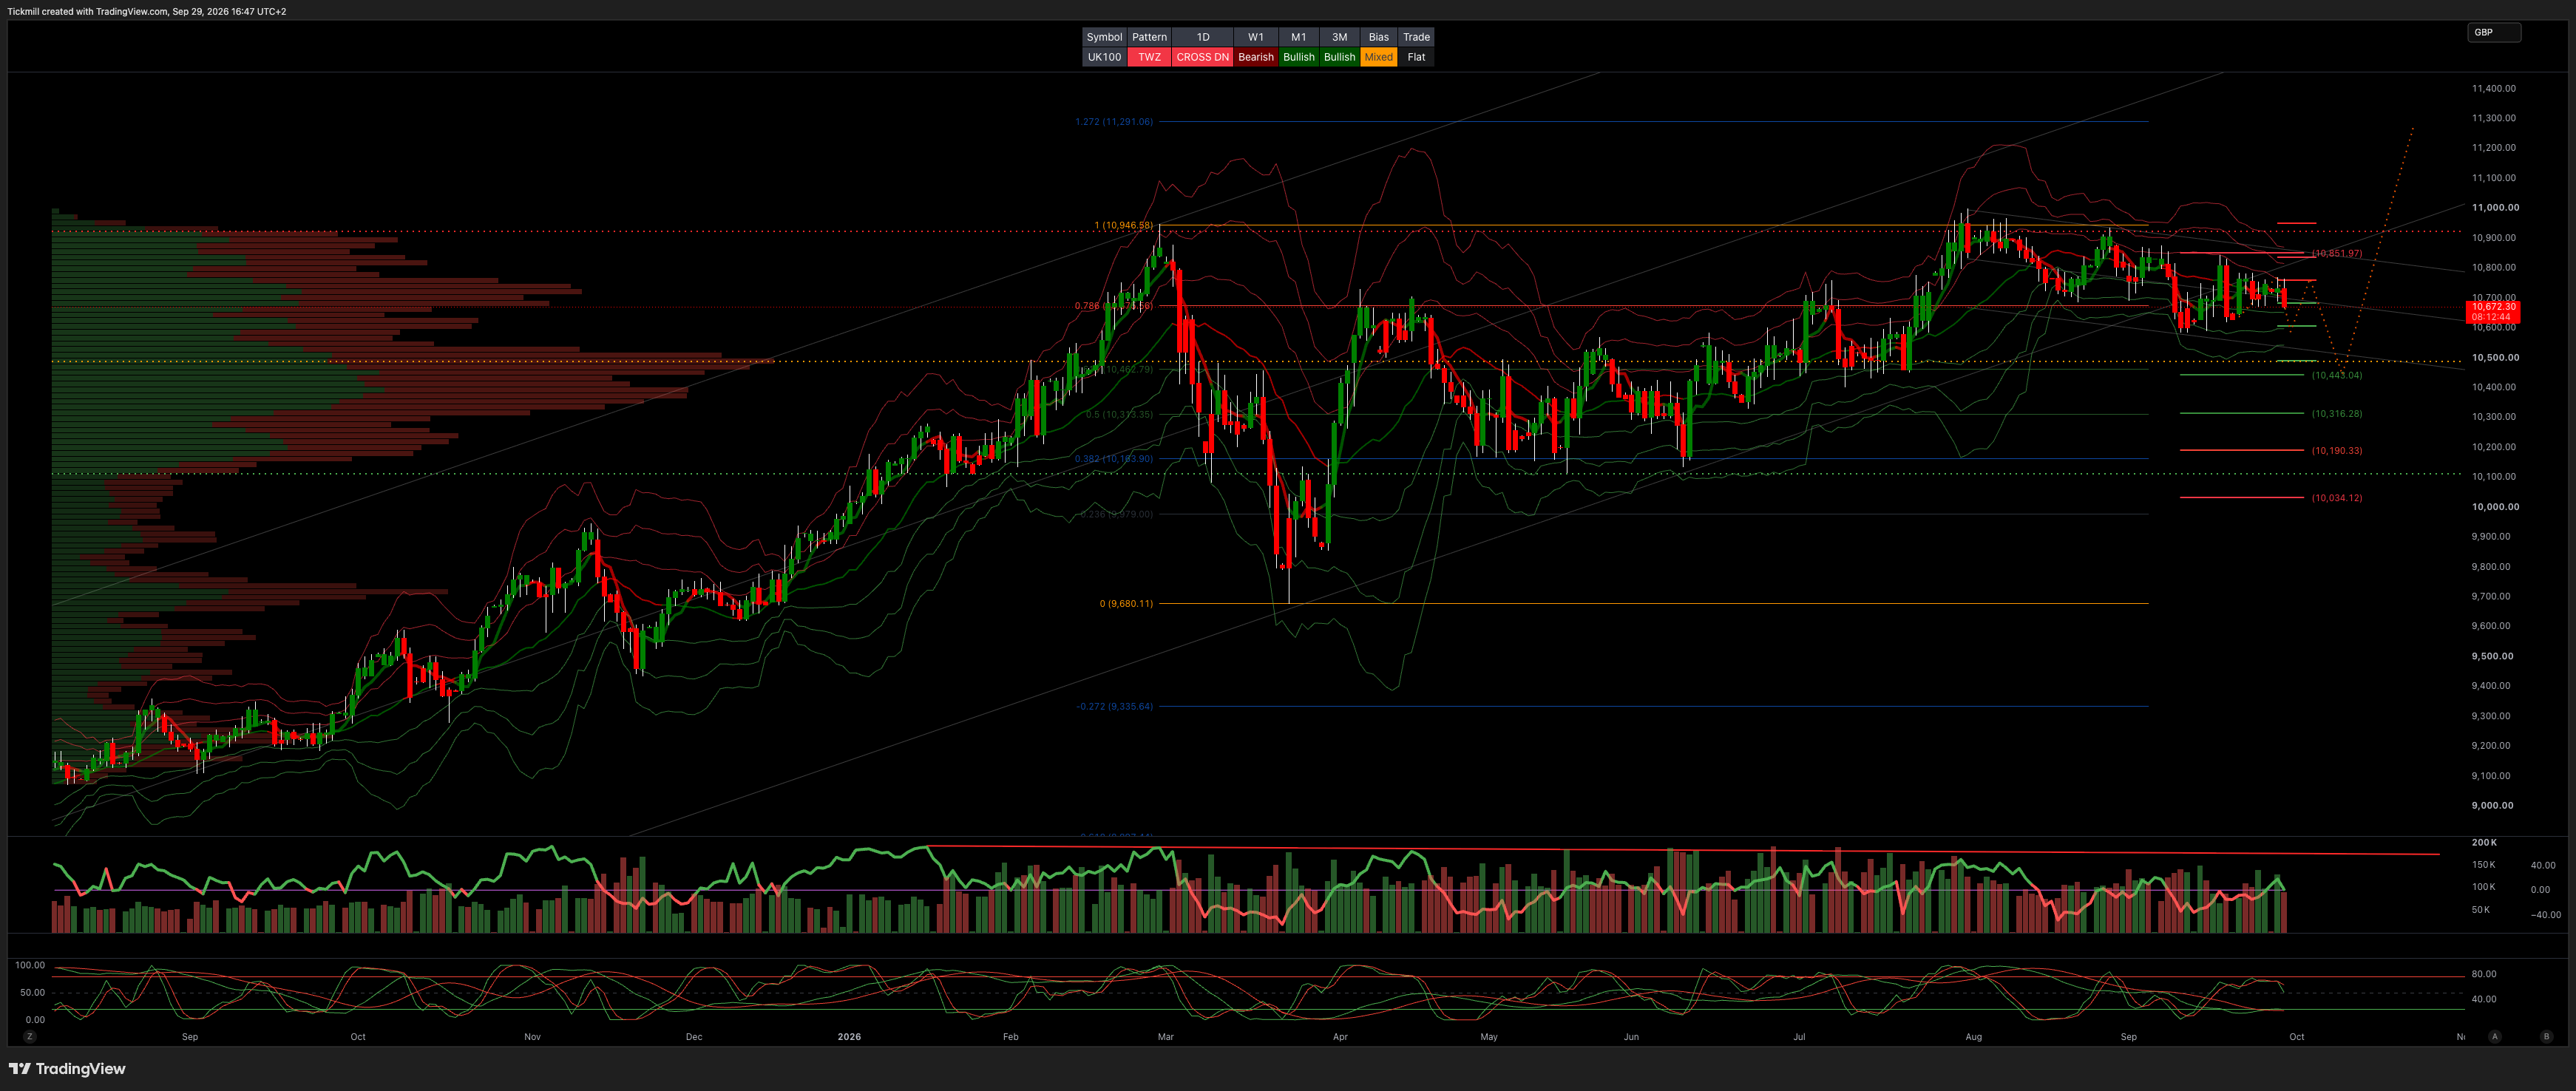
The FTSE 100 surrendered early gains on Tuesday to trade firmly in negative territory, down 61.60 points or 0.57% to 10,672.30. An initial uptick driven by gains in pharmaceuticals and precious metals miners faded as crude oil prices slipped below the flat line, while political rhetoric from the Labour conference and ongoing Middle East impasse weighed on investor sentiment.
Healthcare and resource counters provided early support before broader market weakness took hold. Pharmaceuticals led top-flight upside, with GSK and AstraZeneca advancing 2.5% and 1.9%, respectively. Rebounding precious metal prices lifted miners, where Anglo American Plc, Antofagasta, and Glencore gained 2.3%, 2.2%, and 2.1%, while Fresnillo added 1.3% and Rio Tinto climbed 1.2%. Convatec Group advanced 3.4%, Weir gained about 3%, and Metlen Energy & Metals, Halma, Intercontinental Hotels Group, and Spirax Group added 2.0% to 2.5%. Notable gains were also posted by Airtel Africa, Polar Capital Technology Trust, IMI, Smiths Group, Babcock International, AutoTrader Group, Lloyds Banking Group, British Land, Rolls-Royce Holdings, and Whitbread.
Conversely, energy majors and utilities dragged the index lower into late trading. Oil stocks slipped as Brent crude gave up early gains to trade around $105.10 a barrel after touching an intraday high of $107.87; Ithaca Energy and BP shed 3.4% and 2.1%, respectively, while Shell drifted about 1.0% lower. Selling pressure was particularly concentrated across water and utility stocks—including Severn Trent and Pennon Group—following Prime Minister Andy Burnham’s Labour conference speech, as markets priced in risks of expanded public control and tighter ownership rules. Consumer staples and retail names also traded cautiously amid potential tax changes and household spending squeezes, with British American Tobacco, Admiral Group, Barratt Redrow, Unilever, Sainsbury (J), Diageo, and Kingfisher losing between 1.0% and 1.7%.
On the economic front, the British Retail Consortium reported that UK shop price inflation edged down slightly to 1.4% in September from 1.5% in August, driven by promotional discounting, though remaining above the three-month average of 1.3%. Meanwhile, Sterling softened near $1.32 while Gilt markets remained cautious following fiscal reassurances from Chancellor John Healey.
Finish Line: The FTSE 100’s early rally faded as oil majors slipped and domestic political commentary triggered a pullback in utilities and consumer names. While pharmaceutical strength and a mining bounce provided partial insulation, persistent energy volatility and policy risks surrounding upcoming budget decisions kept the broader market on the defensive.
TECHNICAL & TRADE VIEW – SEE CHART ATTACHED
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% and 73% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
Patrick has been involved in the financial markets for well over a decade as a self-educated professional trader and money manager. Flitting between the roles of market commentator, analyst and mentor, Patrick has improved the technical skills and psychological stance of literally hundreds of traders – coaching them to become savvy market operators!